For years, portions of the construction and restoration industries have encouraged a troubling expectation among homeowners: when a roof ages or major repairs become necessary, wait for the next storm or disaster and let insurance pay for it.
Insurance is intended to protect against covered losses, not serve as a property maintenance program. Yet many consumers treat it as their financial strategy for replacing worn building components. For carriers already managing rising construction costs, catastrophe exposure and underwriting pressure, this mindset adds operational and financial strain.
The Growing Divide Between Coverage and Expectations
As property insurance risks and costs have increased, carriers have adopted measures to manage exposure, including roof payment schedules, actual cash value provisions, higher deductibles and tighter underwriting guidelines.
While these steps manage financial risk, they can leave homeowners facing unexpected expenses after legitimate covered events. The policy may function as written, yet still feel insufficient, fueling disputes and eroding trust. Meanwhile, the physical risk of aging properties remains.
Changing policy provisions may reduce an insurer’s financial exposure, but it does not necessarily reduce the physical risk associated with the property.
Changing the Financial Behavior of Property Ownership
The proposed Property Savings Account (PSA), modeled conceptually after a health savings account, would allow homeowners to set aside tax-advantaged funds for qualified preventive maintenance and property resilience improvements.
Rather than waiting for the next storm or disaster, homeowners could replace aging roofs with Class 4 impact-resistant shingles, potentially reducing damage from future hail events. In wildfire-prone areas, they could invest in Class A fire-rated roofing systems, fire-resistant exterior cladding, defensible space and vegetation management. Homeowners could also replace deteriorating plumbing before a pipe bursts, upgrade outdated electrical systems or improve drainage to reduce water intrusion.
Preventive maintenance preserves a property’s condition, while resilience improvements strengthen its ability to withstand future events. The PSA would help homeowners fund both before a loss occurs.
Why Carriers and Claims Professionals Should Care
Better-maintained, more resilient properties could reduce certain claim frequencies and severities, improve underwriting predictability and lessen disputes where preexisting deterioration complicates the determination of covered damage. These outcomes would need to be demonstrated through actual loss experience rather than assumed.
Claims professionals could contribute by identifying recurring vulnerabilities seen in losses, distinguishing preventive work from post-loss repairs and sharing aggregated insights about which improvements may reduce damage and claims complexity. Underwriters could evaluate documented improvements and determine whether they justify changes in risk assessment or available incentives.
The potential value extends to reinsurance. If improvements are widespread, verifiable, and reflected in credible loss data, carriers may be able to demonstrate better underlying risk to reinsurers. Over time, that evidence could inform catastrophe modeling, risk selection and potentially reinsurance terms, though no pricing benefit is automatic.
A Shared Interest and a Role in Policy Development
Carriers can identify an aging roof or hazardous electrical system, but identifying the vulnerability does not give the homeowner the money to correct it. A dedicated savings mechanism could help close that gap without asking insurers to directly fund each improvement.
The PSA would not replace coverage, diminish contractual claim obligations, or require homeowners to use savings for covered losses. It would provide a separate resource for maintenance and resilience work that insurance was not intended to finance.
Because the proposal envisions tax advantages, congressional committees such as the House Ways and Means Committee would have a role in shaping its viability. Carriers, reinsurers and claims professionals could contribute loss data, identify upgrades associated with measurable risk reduction, and help develop practical standards for qualifying improvements. Industry participation could help make the framework useful for real-world property risk rather than merely theoretical.
Looking Beyond the Next Claim
The insurance industry has invested heavily in catastrophe modeling, risk selection and claims management. But identifying and pricing risk is only part of the equation. Helping homeowners develop the financial capacity to reduce that risk deserves consideration as well.
For insurers, the question is not only how much the next disaster will cost, but how much of that loss could have been prevented through investments made before it occurred. The Property Savings Account offers an opportunity to begin answering that question.
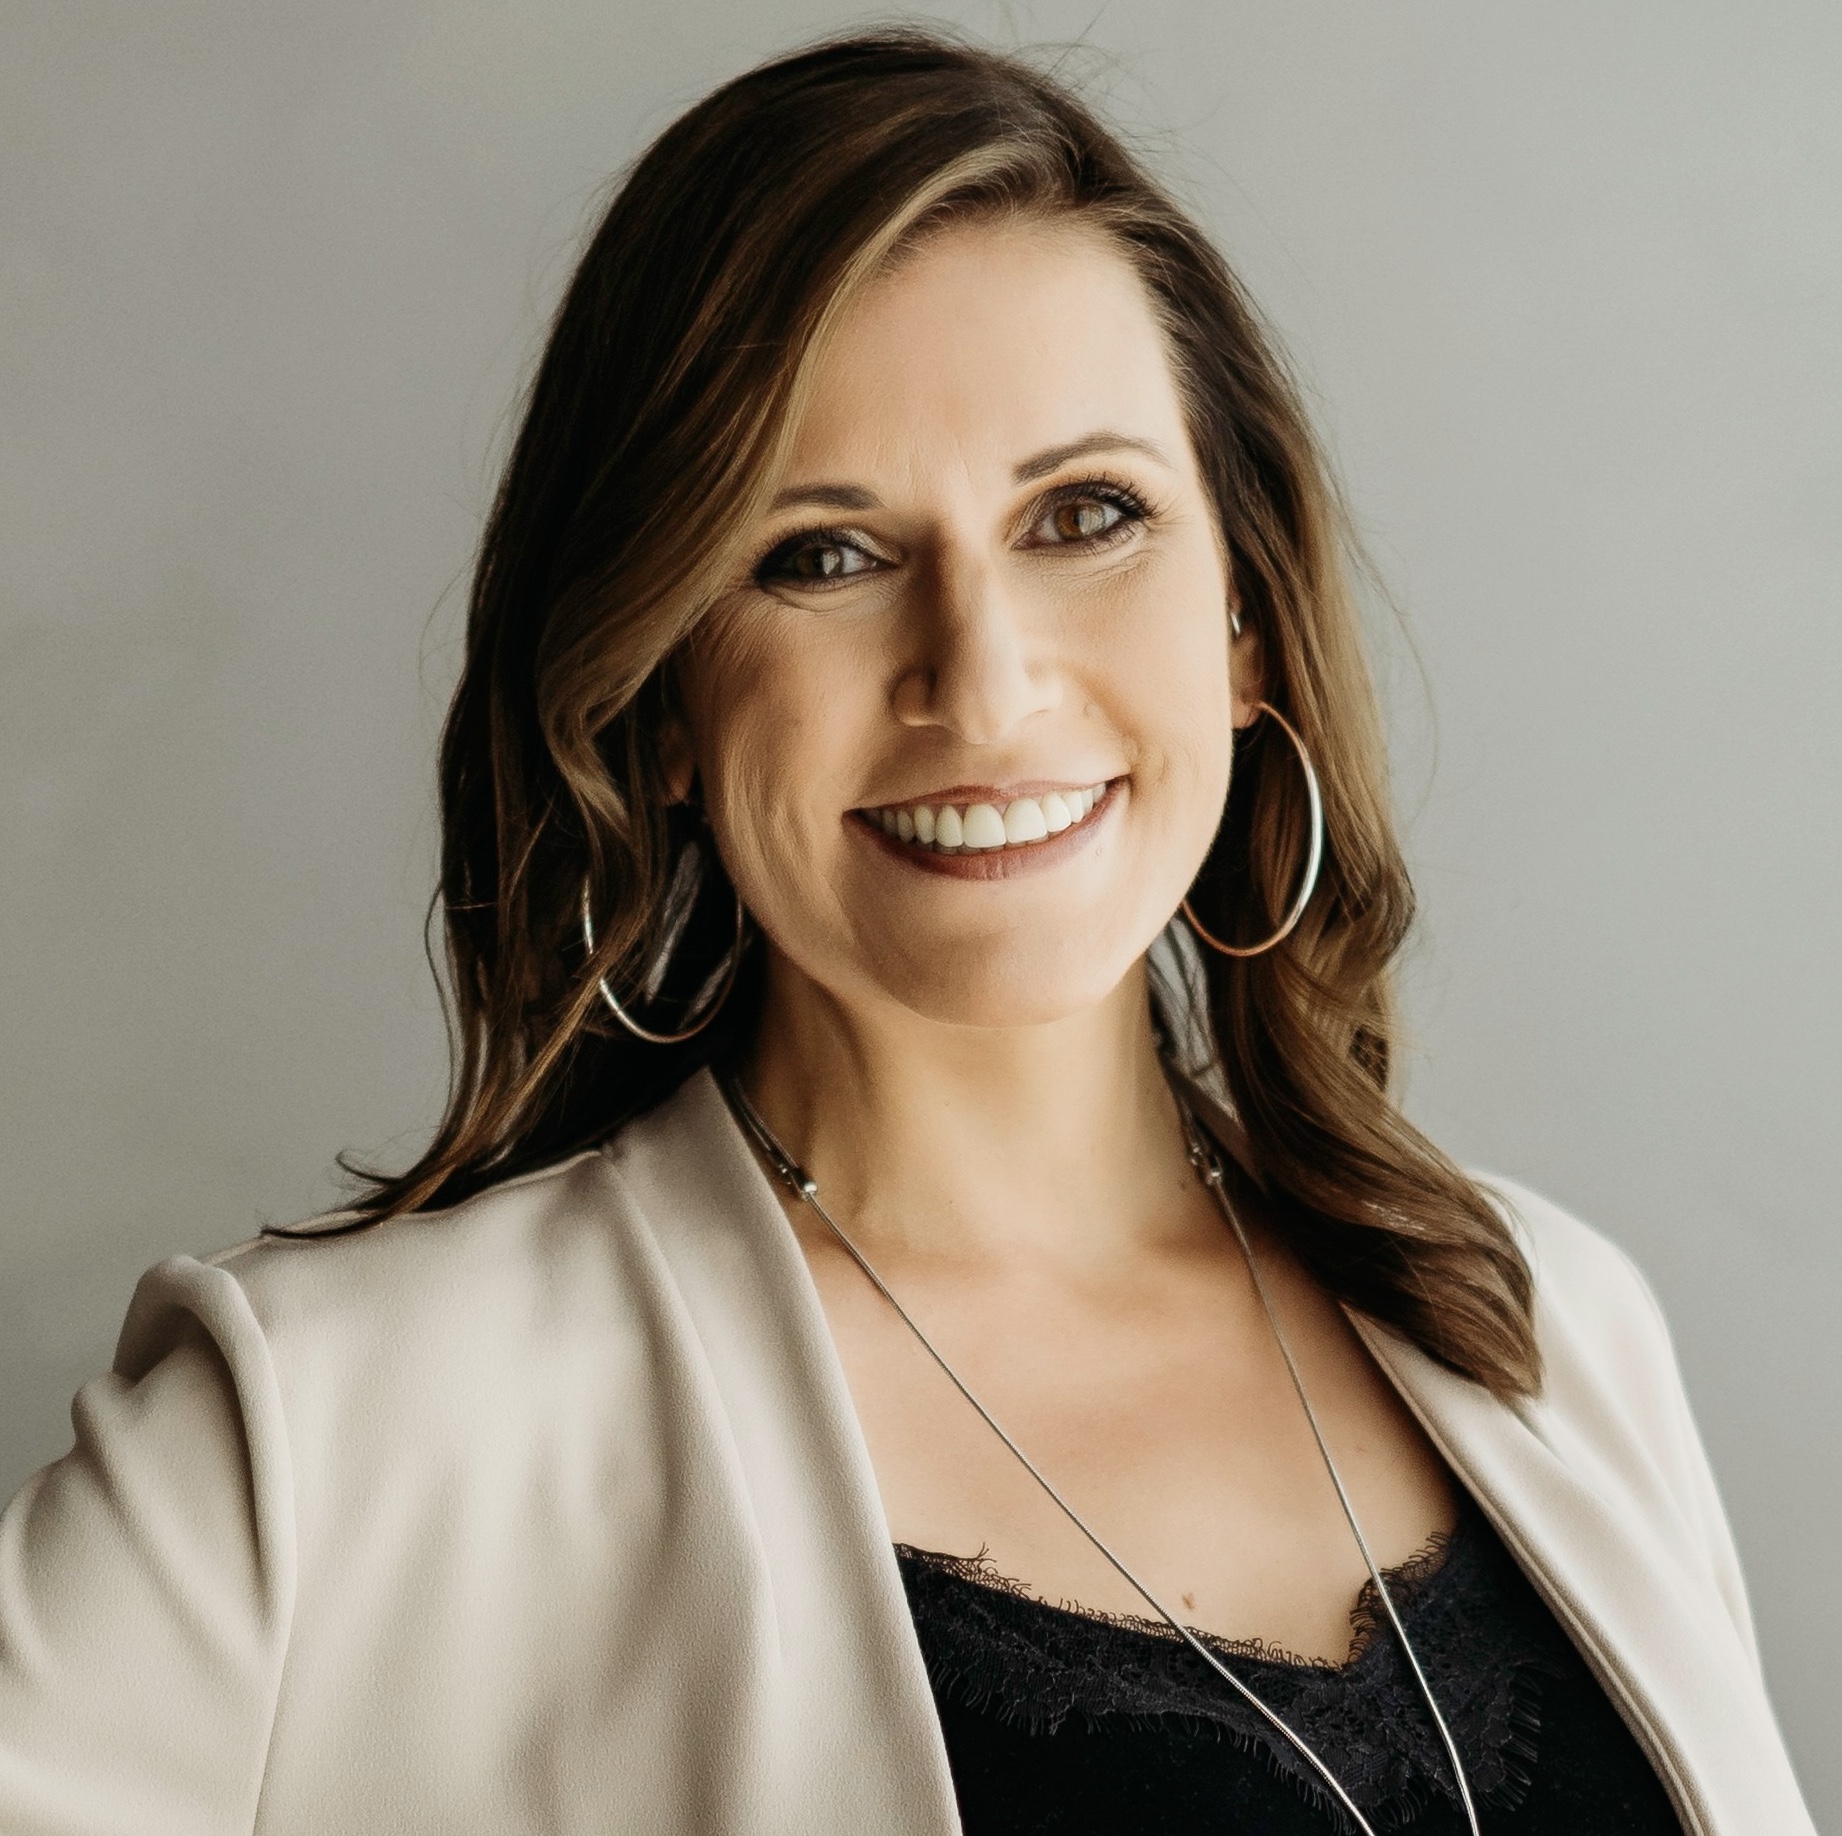
Silver is a licensed general contractor, insurance appraiser, umpire, expert witness, author, and industry advocate whose work bridges construction, property insurance, and disaster resilience. She owns Roofing Utah, and she is the author of The Silver Lining Insurance Playbook and creator of the Property Savings Account (PSA) initiative, a proposed federal tax-advantaged savings framework.
Was this article valuable?
Here are more articles you may enjoy.
 Register: Risky Future AI Tools for MGAs ‘Demo Day’ on November 10
 Berkshire’s Pivot to AI Bets Gets an Immediate Reality Check
 Terror Suit Against Drugmakers Draws US Supreme Court Inquiry
 Manufacturers Hammer IBHS Over 15-Year Roof Age Limit for Fortified Designation
Want to stay up to date?
Get the latest insurance news
sent straight to your inbox.